 | |||||||||
| | |||||||||
 Happy Friday, Fintech Takers! After Wednesday’s newsletter, I was delighted to receive many fantastic suggestions for the classics-inspired playlist that I have been assembling for my daughter. Thank you to everyone who sent in suggestions. Apparently I’m not the only parent who takes musical curation for their kids seriously! The resulting playlist — Get Psyched (by the classics) — is available on Spotify, and, if I might be so bold, makes an excellent audio accompaniment to today’s newsletter! - Alex P.S. — I tried to keep today’s newsletter short because there’s been a lot of content this week, including yesterday’s sponsored deep dive essay (An Accountable Credit Score), which I would love for you to take the time to read, if you haven’t already! P.P.S. — There is still time to register for next week's virtual event — The Science (and Fiction) of Friction — and I'd encourage it. We've been prepping the content all week and it's going to be a really great discussion! Was this email forwarded to you? Sponsored by Bretton At most banks, growth plans get written by the lending team and vetoed by the compliance queue. Life (and Screen Scraping) Finds a WaySometimes, when you take a step back and unfocus your eyes a bit, a pattern becomes clear and, in a brief flash of insight, you see (with seemingly perfect clarity) how the future is going to unfold. A fictional (though still instructive) example can be found in the movie Jurassic Park1, when Dr. Ian Malcolm summarizes the last 65 million years: 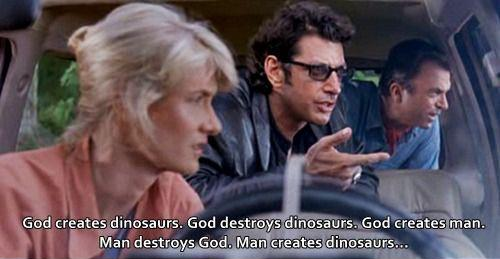 And then Dr. Ellie Sattler humorously, but not inaccurately predicts2 the remainder of the film: 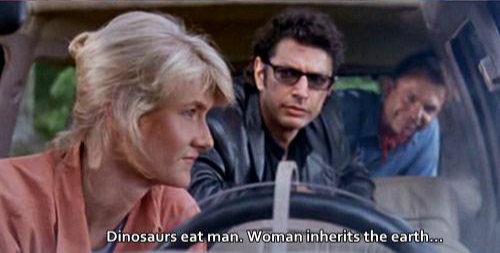 I had a similar flash of insight recently, which I wanted to jot down, for posterity’s sake, if nothing else. It’s not a guarantee of what will happen, obviously. As Yogi Berra reminds us, it's tough to make predictions, especially about the future. However, I do think it’s a useful framework for thinking about the past, present, and future of our industry. In honor of Doctors Malcolm and Sattler, I’ll summarize it like this: Fintech scrapes banks → Banks build APIs → Regulators regulate APIs → Banks sue regulators → AI scrapes banks → Banks build APIs → Regulators regulate APIs → AI sues regulators Allow me to elaborate. What Already HappenedYou know the history, so I’ll move through this part quickly. Fintech companies wanted consumer data in order to build better products and experiences, and to enable them to compete with banks. So, with the permission of those consumers (and armed with their online banking credentials) the fintech companies (via data aggregators like Yodlee and Plaid) scraped the data by logging in as if they were the banks’ customers and hoovering up all of the data they might need.3 I think of this version of screen scraping — which dates back to the early 1990s, but really took off in the 2010s — as the ultimate annoyance to banks. It gestures, vaguely, at a looming competitive threat. And, more concretely, it degrades the performance of their systems, creates all kinds of new security vulnerabilities, and generates a surprising volume of customer complaints. So, in the late 2010s and early 2020s, banks tried to channel all of this operational chaos into a more structured and controllable infrastructure: APIs. Banks — particularly the biggest banks that were seeing a majority of the scraping activity — stood up APIs (generally working off of FDX’s common technical standard) and entered into data access agreements with the individual data aggregators that had been scraping them. Then the regulators showed up. Specifically, the CFPB, which undertook rulemaking on consumer-permissioned data sharing under the authority of Section 1033 of the Dodd-Frank Act. The bureau’s primary motivation, in setting the rules, was to increase market competition and cement permissioned data sharing as a consumer right.4 This effort was strongly supported and celebrated by fintech companies, who knew that screen scraping was expensive and relatively easy for banks to disrupt, and that a regulatory mandate would formalize consumer-permissioned access to banks’ data as a standard industry practice. The prudential regulators (the FDIC, OCC, NCUA, and Fed) mostly stayed out of the effort, which isn’t surprising given that their mandate doesn’t overlap much with issues of fairness and market competition. As you know, this Biden-era rulemaking effort ultimately failed. The big banks5 sued the bureau, arguing that the agency had overstepped its legal authority, and objecting, in particular, to the unfairness of being required to build and maintain APIs and give their data away for free. When control of the CFPB changed hands, the rule was effectively scrapped, and — in an incredibly aggressive move — JPMorgan Chase began charging for access to its open banking APIs. This cemented a new market-based status quo that the big banks seem generally pleased with and that any future open banking rulemaking will need to accommodate. It’s worth asking why this new status quo — consumer-permissioned data sharing via paid APIs — seems as stable as it is.6 I think the reason is that data, as a resource, is something that can be effectively priced, metered, and sold. Fintech companies and data aggregators don’t like having to pay for a raw material that they were accustomed to getting for free, but they are willing to if necessary. Each side uses the leverage they have to negotiate a clearing price, and you end up with an equilibrium that leaves everyone grumbling but functional. This point is important because it will stand in stark contrast to how banks are going to feel when the next version of this fight really gets going. What Might Happen NextAllow me to introduce a couple of new characters in our story:
These are not chatbots. They are personal AI agents. You tell them what you want, and they take action on your behalf. And to do that, guess what they do? They screen scrape! But in a meaningfully different way than the screen scraping we have traditionally seen in open banking. Muse opens a browser and fills out forms on the user’s behalf, and it keeps working after the user closes the app. Instinct, per its own terms, can read and store a copy of the data in any account a user connects to, and it can make purchases and accept agreements in the user's name. These aren't scrapers from a centralized data aggregator hitting a bank’s servers. This is the customer's own AI agent, operating inside the customer's own authenticated session, on the customer's own device. There is no third party for the bank to negotiate with. There is no data-sharing agreement to withhold. There is nothing to cut off, because from the bank's side of the glass, it looks exactly like the customer logged in and did some things.7 Screen scraping 1.0 was expensive and disruptable. That's why fintech companies and data aggregators wanted API-enabled access formalized. Screen scraping 2.0 is the opposite. It's cheap, because LLMs are genuinely good at reading a page and clicking the right thing. And it's nearly impossible to stop, because you can't block an IP range without blocking your own customers, and the traffic isn't coming from an aggregator you can identify and rate-limit. It's coming from everywhere, from everyone, all at once. And, unfortunately, when mistakes happen — and there will be mistakes because AI agents are going to misread pages and take actions that their human counterparts did not intend — the consequences will still land, in many cases, with banks. This won't really be fair, and it often won't even be the bank's legal responsibility, but it will be the practical reality. Just as banks ended up getting in trouble with their customers (and eventually with regulators and lawmakers) when their customers’ open banking connections broke or when their customers authorized payments to scammers, so too will banks bear the brunt of their customers’ displeasure when their personal AI agents screw up something financial. So, the question is: What will banks do about this new AI agent threat? Well, we know what they’ll want to do. They’ll want to follow the same playbook as last time. They’ll want to wrangle all of this operational chaos into something that can be channeled and controlled. They’ll want to force AI agents to go through APIs (or MCP servers, or whatever the appropriate technical solution ends up being for AI agents). It will be much harder this time than it was last time. In the screen scraping 1.0 fight, banks had leverage. Fintech companies and data aggregators entered into restrictive data access agreements with the big banks because they knew that while screen scraping was always a fallback option, it was sufficiently expensive and brittle as to be a very unappealing one. That’s not the case with screen scraping 2.0. AI companies don’t have the same incentives that fintech companies and data aggregators had. Their approach to screen scraping — decentralized and powered by LLMs — is much cheaper and more resilient. It’s practically impossible for the companies on the other side of the agentic transaction to stop. And, in the case of agentic finance, banks will want to stop it. AI agents, armed with consumers’ identity information and bank account credentials, can create a lot of value for consumers by leveling a playing field that has, for decades, been tilted by inertia and information asymmetry. They will, for example, be able to check a consumer’s checking account balance, sweep excess deposits into a savings account, and, when that savings account fails to keep its pricing competitive, open a new, higher-yielding savings account and move the money over to it. All automatically. All run entirely within the consumer’s own session, with their cookies and from their IP address. It’ll be amazingly valuable for consumers (a tireless deposit broker in your pocket!) and, simultaneously, the biggest threat to net interest income in the history of banking. And, for what it’s worth, the market is already beginning to price in this threat. On September 22nd, bank, brokerage, and insurance stocks sold off hard, and the explicit fear — named in the reporting — was disruption to businesses that live on "consumer inertia," the tendency to keep buying something out of habit even when a better alternative exists. The specific worry is that if consumers let AI agents relocate capital between providers, financial firms will struggle to hold deposits, intensifying competition on rates and fees. This worry will only grow as adoption of personal AI agents continues to climb. So, what will banks do? My guess — and the irony here will be absolutely intoxicating — is that banks will turn to the government for help. In fact, I’d bet that banks will practically beg regulators and lawmakers to save them from agentic AI. Last time, regulation on consumer-permissioned access was an offensive weapon: Led by the CFPB, cheered on by the market disruptors, and explicitly pro-competition in its framing. Next time, regulation will be defensive, and the banks — who were firmly against mandated APIs for consumer-permissioned access — will be the ones demanding it. They won’t be able to stop AI agents. They'll be absorbing the customer fallout. And most existentially, their net interest income — the money they earn by paying you little on deposits and lending that money out for more — will be getting compressed to nothing as AI agents relentlessly optimize every customer's financial situation. Next time, I predict, the regulatory push will be spearheaded by the prudential regulators, even if the legal vehicle and implementing agency are nominally Section 1033 and the CFPB. In fact, it’s possible that Congress may actually shake off its lethargy and write a new law to empower the FDIC, OCC, NCUA, and Fed to take action. In the fight over the Clarity Act, we just saw how deeply sympathetic lawmakers on both sides of the aisle are to community banks’ fears of deposit displacement.8 In the case of stablecoins, that fear seemed (to me) a bit overblown. With AI agents, it won’t be. When agent-driven optimization threatens banks' ability to fund themselves and perform maturity transformation, you will see a sudden and overwhelming safety-and-soundness instinct kick in among policymakers. The resulting regulation will prohibit AI agents from scraping bank systems, designate the banks' APIs/MCPs as the only sanctioned channel for access, and — most controversially — rate-limit how much a customer's AI agent is allowed to optimize their own finances. If that sounds absurd, remember that we have done this before. Regulation Q and Regulation D were, in effect, government-imposed limits on how efficiently your money was allowed to work — caps on deposit interest, limits on how often you could move savings — designed to protect banks' margins and their capacity to lend. We built synthetic friction into the system on purpose, because a little inefficiency in how money moves is (arguably) necessary to keep the machine of credit creation humming. However, if such regulation were to be implemented, it would be enormously controversial. And unlike our current moment in open banking, I don’t think there would be a natural equilibrium point for the market to settle out at. This fight won’t be about how to price a valuable-but-quantifiable asset (data). It will be about inertia and the binary choice that we, as a society, will have to make about whether to allow technology to strip it out of our financial system, or whether to use the law to artificially maintain it. I know where banks and their prudential regulators will come down on that question. And I think I know where a majority of Congress will come down on it as well. And, because of that, I feel very confident in this prediction (which brings us full circle): The companies offering personal AI agents will immediately file suit to stop it. Fintech scrapes banks → Banks build APIs → Regulators regulate APIs → Banks sue regulators → AI scrapes banks → Banks build APIs → Regulators regulate APIs → AI sues regulators WHERE I'LL BE ✈️ AI-Native Banking & Fintech Conference | September 29 | Salt Lake CityNext week! I’m very excited! If you’ll be there, let me know! 💻 The Science (and Fiction) of Friction | September 30 | VirtualThis will be a really fun virtual event, where me and Tomas Campos, CEO of Spinwheel, will be poking at some really important assumptions in digital lending. Join us! ✈️ Money20/20 | October 18-21 | Las VegasPhew! I’m already tired, just thinking about it. But I’m also excited to see everyone and to participate in some really exciting sessions and side events, including 3x3 basketball (Sign up! There’s still room!) Thanks for the read! Let me know what you thought by replying back to this email. — Alex Footnotes
| |||||||||
|